Securing financing for a funeral home is an important financial decision, and understanding the timeline can make the process considerably easier. Whether the goal is to purchase an established funeral home, refinance existing debt, acquire commercial real estate, or invest in new equipment, borrowers need to plan for more than simply submitting a loan application.
The business financing process typically involves several stages, including financial preparation, application, underwriting, due diligence, approval, and closing. While every transaction is different, having a realistic timeline helps business owners organize documents, anticipate lender requests, and avoid unnecessary delays.
1. Start With Financial Preparation
The loan timeline begins before the application reaches a lender. Strong preparation can make the rest of the process more efficient.
Funeral home owners should first determine how much financing they actually need and what the funds will accomplish. An acquisition may require money for the business purchase, real estate, working capital, closing expenses, and equipment. An existing operator may instead need financing for expansion, renovations, vehicles, technology, or refinancing.
Lenders generally want to understand the company’s financial performance and ability to repay the proposed debt. Borrowers should therefore review revenue, operating expenses, existing liabilities, cash flow, assets, and available liquidity.
Documents such as business tax returns, financial statements, bank statements, debt schedules, and personal financial information may also be needed.
This preparation stage can take anywhere from several days to several weeks depending on how organized the borrower and business records are. Spending time here can prevent larger delays later.
2. Submit the Application and Supporting Documents
Once the financial package is ready, the borrower can move into the formal application stage.
The lender will typically request information about the business, ownership, financing purpose, requested loan amount, collateral, and financial history. For an acquisition, the lender may also need information about the seller and the business being purchased.
Accuracy is especially important during this stage. Financial statements, tax returns, bank records, and other documents should be consistent. Differences between documents may lead to additional questions and extend the review period.
The speed of this stage depends partly on how quickly the borrower can provide requested information. A complete application allows the lender to begin evaluating the transaction without waiting for missing documents.
This is an important part of the funeral loan approval timeline, because incomplete information can push an otherwise straightforward application backward.
3. Understand the Underwriting and Due-Diligence Stage
After the application is submitted, the lender moves into underwriting. This is often the most detailed part of the business financing process.
Underwriters evaluate whether the business has sufficient financial strength to support the proposed loan. They may analyze historical cash flow, profitability, debt obligations, credit history, collateral, management experience, and projected performance.
For funeral home acquisitions, lenders may also examine the target company’s financial statements, real estate, equipment, lease arrangements, and other assets. Depending on the transaction, appraisals, environmental reports, insurance documentation, or additional professional reviews may be required.
The lender may ask follow-up questions during this stage. This is normal and does not automatically indicate a problem with the application.
Borrowers can help keep the process moving by responding promptly and providing clear explanations when questions arise.
The underwriting stage can vary significantly. A relatively straightforward transaction may move through review quickly, while a larger acquisition involving real estate, multiple entities, or complex financial records can require substantially more time.
4. Receive Approval and Satisfy Loan Conditions
Once underwriting is substantially complete, the lender may issue a formal approval or conditional approval.
An approval generally outlines the proposed loan structure and may include conditions that must be satisfied before funding. These conditions can involve updated financial statements, insurance, appraisal results, legal documentation, collateral verification, or other requirements.
Borrowers should review the proposed financing carefully. Important items may include the interest rate, loan term, amortization schedule, fees, collateral requirements, guarantees, repayment obligations, and any applicable covenants.
At this point, the borrower should also avoid making major financial changes without discussing them with the lender. Taking on additional debt, moving significant assets, or changing the ownership structure can potentially affect the transaction.
The final approval stage may take days or longer depending on how quickly outstanding conditions are completed.
5. Focus on Loan Closing Preparation
After approval conditions are satisfied, the transaction moves toward closing. Loan closing preparation is an important stage because several parties may need to coordinate before the funds can be released.
Depending on the transaction, participants can include the borrower, lender, attorneys, accountants, title professionals, insurance providers, and the seller.
Closing documents must be reviewed and signed correctly. Collateral documents, insurance requirements, purchase agreements, title documents, and other legal paperwork may need to be finalized.
For an acquisition, the closing date may also need to coordinate with the seller and other professionals involved in transferring ownership.
Borrowers should carefully review all final documents before signing and ask qualified professionals about anything they do not understand.
A well-organized closing process can help prevent last-minute problems and keep the transaction on schedule.
6. Funding and Managing the Loan After Closing
The final stage is funding. Once all closing conditions have been completed, the lender can release the loan proceeds according to the agreed structure.
At this point, the borrower should immediately incorporate the new debt into the business’s financial management system. Monthly loan payments, interest expenses, insurance costs, and other obligations should be included in cash-flow planning.
For an acquisition, owners should also monitor the business against the financial projections used during underwriting. Tracking revenue, expenses, operating margins, and debt-service performance can help identify problems early.
The funeral loan approval timeline does not truly end with funding. Responsible post-closing management is essential for maintaining financial stability and creating a strong record for future financing needs.
Conclusion
The time required to secure a funeral home loan depends on the complexity of the transaction, the lender, the borrower’s financial readiness, and how quickly documentation and due-diligence requirements are completed.
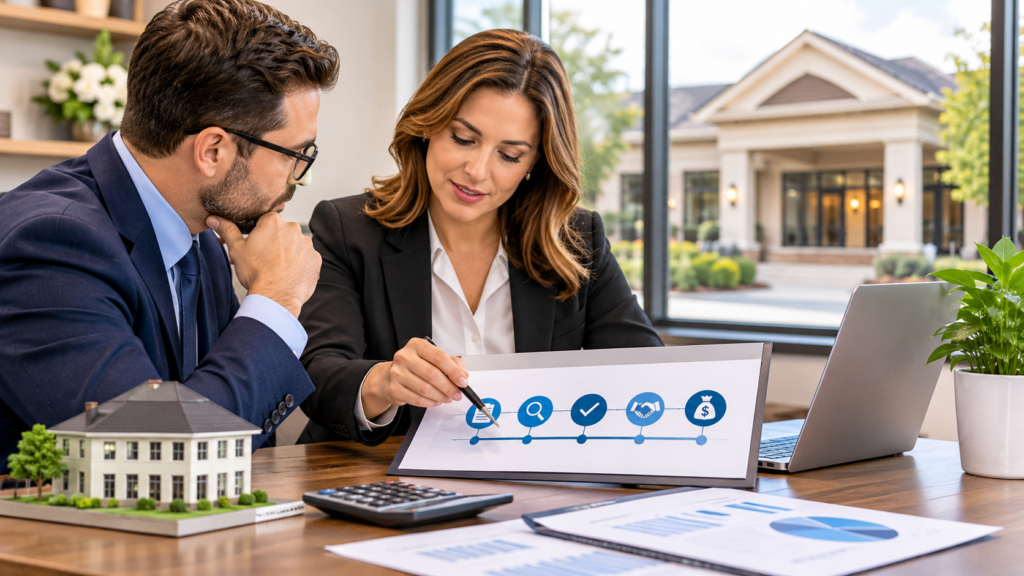
Rather than focusing on a single number of days, borrowers should think of the process as a sequence: financial preparation, application, underwriting, approval, loan closing preparation, and funding.
The best way to shorten unnecessary delays is to prepare early, maintain accurate financial records, respond quickly to lender questions, and understand the requirements of the financing structure.
For funeral home owners, thoughtful preparation can turn an unfamiliar lending process into a manageable series of steps. With a clear understanding of the business financing process, borrowers can approach lenders with greater confidence and position their business for a smoother path from application to funding.