Selling an established business is one of the most important financial and personal decisions an owner can make. For funeral home owners, the process can be especially sensitive because the business represents years of professional experience, community relationships, family involvement, and a reputation built on serving families during difficult times. Finding someone willing to purchase the business is only the beginning. Finding someone capable of completing the transaction and respecting what has been built is far more important.
Not every interested buyer is a qualified buyer. Some may have genuine intentions but lack sufficient financing, while others may be exploring opportunities without being prepared to make a serious commitment. Understanding the difference can help sellers avoid wasted time, unnecessary disclosure of confidential information, and unsuccessful negotiations.
When choosing a qualified funeral home buyer, sellers should look beyond the proposed purchase price. Financial strength, professional experience, transparency, communication, and a realistic acquisition plan all help determine whether a potential buyer deserves consideration.
1. Financial Capability Is the First Sign of a Serious Buyer
A trustworthy buyer must demonstrate the financial ability to complete the purchase. Attractive offers can create excitement, but a high purchase price means little if the buyer cannot secure the necessary funding.
Before moving into detailed negotiations, sellers should request reasonable evidence of financial qualifications. This may include proof of available funds, a bank financing prequalification, lender communication, or documentation showing the buyer has access to sufficient capital.
For funeral home acquisitions, financing requirements may vary depending on whether the transaction includes the operating business, real estate, equipment, or a combination of assets. Buyers should understand these requirements and have a realistic strategy for funding the transaction.
Sellers should also consider whether the buyer has accounted for additional expenses, including legal fees, working capital, closing costs, and potential operational improvements.
A financially prepared buyer is generally more capable of moving through due diligence and reaching closing without unnecessary delays. Verifying financial readiness early helps sellers focus their attention on opportunities with a realistic chance of success.
2. Professional Experience and Industry Understanding Matter
Financial resources are important, but they are not the only measure of a buyer’s suitability. Experience and understanding of the business can significantly influence how smoothly ownership changes hands.
Funeral homes operate differently from many other businesses. Their success depends on community trust, professional standards, experienced employees, regulatory compliance, and relationships with families. A buyer who understands these responsibilities is more likely to recognize the value of the existing operation.
Industry experience can be particularly valuable when evaluating operational challenges, employee retention, service quality, and long-term business planning. However, a buyer does not necessarily need to own another funeral home to be qualified. An experienced business operator with a capable management team and a clear transition strategy may also be a strong candidate.
During discussions, sellers should ask about the buyer’s previous acquisitions, business management experience, understanding of funeral service operations, and plans for maintaining continuity.
The objective is not simply to find someone who can purchase the property and assets. It is to identify someone who understands the responsibility associated with taking over an established business.
3. Transparency Is Essential When Screening Potential Business Buyers
Trustworthy buyers communicate openly and provide relevant information when requested. They understand that sellers also need to evaluate their qualifications before sharing sensitive business details.
Screening potential business buyers should involve a structured process that allows both parties to establish confidence gradually. Sellers can begin by reviewing a buyer’s professional background, acquisition objectives, financial readiness, and general transaction expectations.
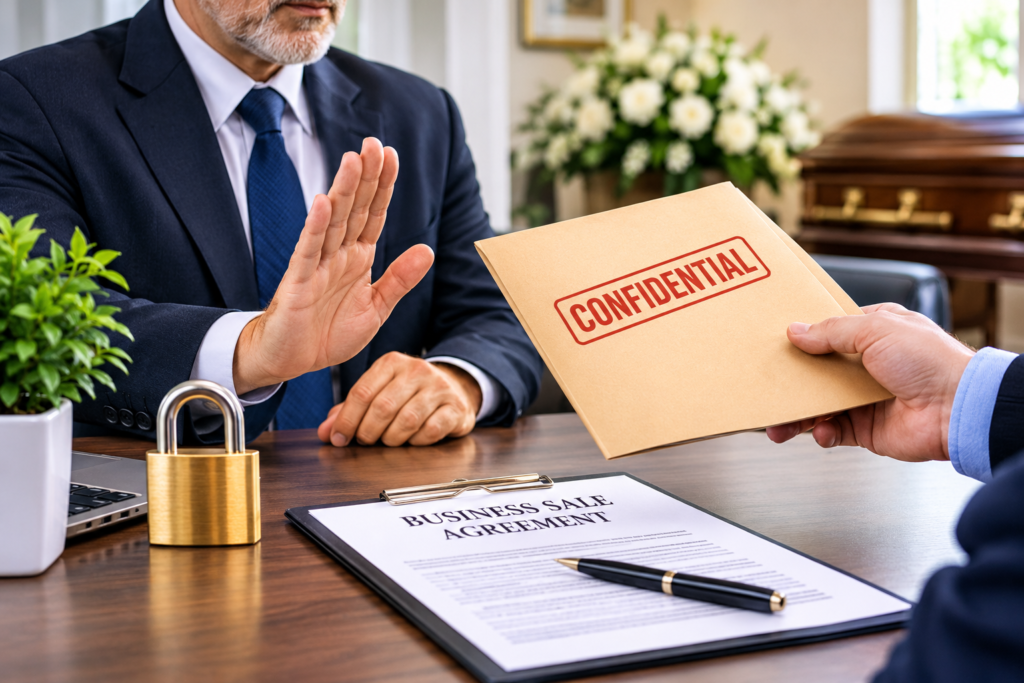
A confidentiality agreement should normally be signed before sensitive information is disclosed. This helps protect financial records, employee information, customer-related details, and other commercially valuable material.
A serious buyer should be comfortable explaining why they are interested in the acquisition, what type of business they want to purchase, and how they expect to finance the transaction.
Warning signs may include refusing to provide basic financial information, requesting confidential documents too early, making unrealistic promises, or avoiding reasonable questions.
Transparency does not mean revealing every detail immediately. Instead, it means creating a professional environment where information is exchanged at the appropriate stage and both parties understand their responsibilities.
4. Realistic Offers and Professional Negotiation Show Genuine Intent
A trustworthy buyer understands that an established business has measurable value. Their offer should reflect financial performance, assets, property value, market conditions, customer relationships, and future opportunities.
An unusually high offer without supporting financial reasoning deserves careful examination. Sometimes buyers make aggressive proposals simply to secure access to confidential information or gain an advantage during negotiations.
A serious buyer generally approaches valuation with reasonable questions and an understanding of the factors affecting the purchase price. They may request financial statements, revenue history, operating expenses, asset details, and other information during due diligence.
Professional negotiation is another important indicator. Qualified buyers communicate clearly, respect agreed timelines, and discuss disagreements constructively. They understand that negotiations involve balancing the seller’s expectations with the financial realities of the acquisition.
Sellers should also evaluate proposed deal structures. Cash purchases, conventional bank financing, SBA-backed financing, and seller financing can create different levels of risk and require different protections.
The best offer is not always the highest one. A slightly lower offer supported by reliable financing and reasonable terms may provide a much stronger opportunity for a successful closing.
5. A Clear Transition Plan Protects the Business’s Future
A business sale does not end when both parties agree on a purchase price. The transition between ownership can influence employees, customers, suppliers, and the overall stability of the operation.
This is particularly important for funeral homes, where established community relationships and service standards are central to long-term success.
When evaluating a serious buyer, sellers should understand how the prospective owner intends to manage the transition. Will existing employees remain in their positions? Does the buyer plan to retain current management? How will customer relationships and community connections be maintained?
A well-prepared buyer should have thoughtful answers to these questions. They may also propose a reasonable transition period during which the current owner helps introduce important contacts, explain established procedures, and support operational continuity.
Sellers should pay attention to whether the buyer appreciates the business’s existing reputation rather than treating the acquisition as nothing more than a collection of physical assets.
A practical transition plan demonstrates preparation and reduces uncertainty for everyone involved.
6. Professional Guidance Helps Sellers Make Better Decisions
Even experienced business owners can find it difficult to evaluate buyers objectively while managing negotiations and daily operations. This is where experienced transaction professionals can provide valuable support.
A funeral home transaction advisor can help organize the selling process, identify qualified prospects, coordinate confidentiality agreements, review offers, and manage communication between interested parties.
Professional guidance can also help sellers distinguish between buyers who are genuinely prepared to complete a transaction and those who are simply exploring the market.
Legal and financial professionals should review important transaction documents, financing arrangements, purchase agreements, and closing conditions. This is especially important when seller financing, real estate, or complex asset structures are involved.
Having the right professional team helps sellers maintain confidentiality, reduce avoidable risks, and make decisions based on reliable information rather than assumptions.
Ultimately, the goal is to create a transaction that protects the seller’s financial interests while giving the buyer a fair opportunity to acquire a valuable business.
Final Thoughts: Choose the Right Buyer, Not Just the Highest Offer
Selling an established funeral home requires more than finding someone willing to pay the asking price. The right buyer should have the financial resources, professional credibility, realistic expectations, and operational understanding needed to complete the acquisition successfully.
By verifying financial qualifications, reviewing relevant experience, maintaining confidentiality, examining offer terms, and discussing transition plans, sellers can make more informed decisions throughout the process.
A carefully managed buyer selection process can reduce uncertainty and help protect the value of years of hard work.
At 4BSF, funeral home owners can explore professional guidance for buying, selling, financing, and refinancing funeral businesses. Whether you are preparing to enter the market or already receiving offers, having experienced transaction support can make a meaningful difference.
Before accepting an offer, take the time to evaluate the person behind it. The right buyer is someone who can deliver on their commitments and help secure the next chapter of your business.