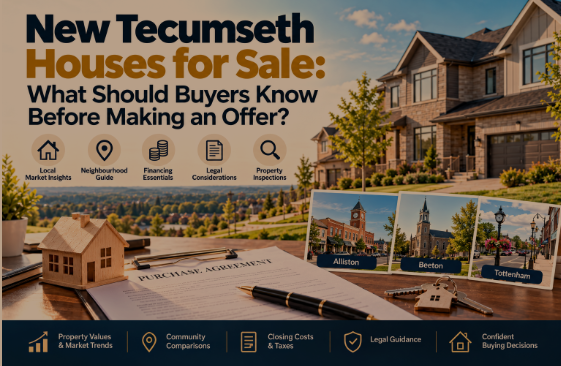
New Tecumseth has become an attractive residential destination for buyers seeking community-focused living in Ontario. Located in Simcoe County, the municipality includes Alliston, Beeton, and Tottenham, each offering distinct housing options and lifestyles. However, finding the right property requires more than selecting an appealing neighbourhood or comparing advertised prices.
Buyers exploring new tecumseth houses for sale should evaluate local market conditions, property values, financing requirements, and legal obligations. These considerations influence purchasing decisions and long-term ownership expenses.
Before submitting an offer, understanding comparable sales, inspection requirements, and contractual conditions is essential. A well-informed approach allows purchasers to assess properties objectively while maintaining realistic financial expectations.
Understanding the Local Real Estate Market Before Purchasing a Home
The New Tecumseth housing market includes detached houses, townhomes, semi-detached properties, and newer residential developments. Property values vary depending on location, construction quality, housing demand, and available inventory. Therefore, understanding local market conditions provides valuable context before buyers enter negotiations.
How Housing Prices and Market Trends Influence Buying Decisions
Housing prices reflect several interconnected factors, including buyer demand, listing inventory, property features, and broader economic conditions. A property’s advertised price represents the seller’s expectations rather than its confirmed market value.
According to Toronto Regional Real Estate Board figures, New Tecumseth recorded an average selling price of approximately $807,218 in September 2026. Local REALTOR® Darren Cabral also reported 54 transactions and approximately 5.2 months of inventory that month. These figures provide historical context rather than a valuation for an individual property.
Furthermore, the number of active listings influences how buyers approach negotiations. Greater inventory may create additional choices, while limited availability can increase competition for desirable homes.
Days on market also deserve attention because extended listing periods may indicate pricing concerns or narrower buyer demand. However, property condition and seller circumstances can influence listing duration.
Why Market Timing Matters When Entering the Property Market
Market timing influences negotiating conditions, but predicting future price movements remains uncertain. Buyers should focus on current affordability and property suitability rather than attempting to identify the perfect purchasing moment.
In competitive conditions, attractive properties may receive multiple offers. Conversely, greater inventory can create opportunities for buyers to negotiate prices, closing dates, or contractual conditions.
Ontario real estate professionals commonly evaluate recent sales, listing activity, and months of inventory when discussing market conditions. These indicators provide useful context, although individual properties may behave differently from broader market averages.
Ultimately, buyers should base purchasing decisions on reliable financial preparation and verified local information.
Choosing the Right Community for Long-Term Residential Value
New Tecumseth contains communities with different residential characteristics, amenities, and commuting considerations. Choosing a suitable location involves evaluating daily convenience alongside long-term household priorities.
For purchasers researching new tecumseth houses for sale, comparing Alliston, Beeton, and Tottenham can clarify which community best matches their requirements.
Alliston, Beeton, and Tottenham: Comparing Residential Opportunities
Alliston offers an established residential environment with commercial services, shopping options, healthcare facilities, and recreational amenities. Its mix of existing neighbourhoods and newer developments appeals to buyers seeking everyday convenience.
Beeton offers a smaller community setting with established residential streets and local amenities. Buyers considering this area should examine property availability, access to services, and their preferred housing characteristics.
Tottenham features established neighbourhoods and residential development within the southern portion of New Tecumseth. Its location may appeal to households balancing community living with regional commuting needs.
| Community | Residential Characteristics | Primary Buying Considerations |
| Alliston | Established neighbourhoods, varied housing options, and commercial amenities | Shopping access, healthcare, schools, and housing selection |
| Beeton | Smaller community environment with established residential properties | Property availability, local services, and lifestyle preferences |
| Tottenham | Residential neighbourhoods with regional road connections | Commuting needs, housing characteristics, and everyday amenities |
No single community represents the ideal choice for every purchaser. Individual priorities, property availability, and affordability should determine the final decision.
Evaluating Location, Connectivity, and Everyday Convenience
A property’s location influences everyday routines, transportation expenses, and future resale appeal. Therefore, buyers should consider proximity to schools, healthcare services, grocery stores, recreation facilities, and employment opportunities.
Commuting requirements also deserve careful evaluation. Residents travelling toward Barrie or the Greater Toronto Area should consider road connections and typical traffic conditions.
Accessibility may influence property demand over time, but convenient transportation does not guarantee future appreciation. Likewise, nearby development can introduce both opportunities and additional traffic or construction activity.
Buyers should evaluate whether the surrounding environment aligns with their household’s practical needs and expected ownership period.
Evaluating Property Prices Beyond the Advertised Listing Amount
An attractive listing price does not automatically indicate strong property value. Buyers need reliable comparisons and a detailed understanding of the home’s condition before determining an appropriate offer.
Professional market analysis considers actual transactions rather than depending exclusively on advertised asking prices.
Using Comparable Property Sales to Assess Fair Market Value
A comparative market analysis examines recently sold properties with characteristics similar to the subject home. Relevant comparisons include location, living area, construction age, lot dimensions, condition, and property type.
For example, comparing a renovated detached home with an older townhouse could produce misleading conclusions. Differences in construction quality and maintenance requirements may justify substantial price variations.
Completed transactions generally provide stronger pricing evidence than active listings. However, current listings can reveal competing inventory and seller expectations.
A qualified real estate professional can interpret these comparisons while accounting for unusual property features or changing market conditions.
How can buyers determine whether a house is fairly priced? A reasonable asking price should align with recent comparable sales, property condition, location, and current market activity. Buyers should examine similar completed transactions and consider necessary repairs. Professional market analysis provides additional context when a property’s features differ from nearby homes.
Identifying Property Features That Influence Future Resale Potential
Construction quality, maintenance history, usable living space, and location can influence a property’s long-term market appeal. Homes with functional layouts and documented maintenance may attract broader buyer interest.
However, resale potential depends on future economic conditions, neighbourhood development, and housing demand. Buyers should avoid assuming that every property will appreciate consistently.
Significant repair requirements may also affect future resale opportunities. Roofing systems, foundations, heating equipment, and drainage conditions deserve particular attention.
A balanced assessment considers both immediate suitability and potential ownership expenses over time.
Financial Planning Essentials for a Confident Home Purchase
Financial preparation establishes practical purchasing boundaries and reduces the likelihood of unexpected complications. Buyers should understand their mortgage capacity, down payment requirements, closing expenses, and ongoing ownership obligations.
A property may appear affordable based on its asking price while creating substantial monthly financial commitments.
Understanding Mortgage Pre-Approval and Purchasing Capacity
Mortgage pre-approval provides an initial estimate of potential borrowing capacity based on financial information and lender criteria. However, it does not guarantee final financing approval.
Lenders may reassess employment income, credit history, debt obligations, and property valuation before approving a mortgage. Interest rates and qualification requirements can also affect affordability.
Buyers should examine monthly mortgage payments alongside insurance, utilities, property taxes, and maintenance expenses. A realistic budget accounts for these recurring obligations without relying entirely on the maximum approved loan amount.
Financial institutions and qualified mortgage professionals can explain available financing structures and applicable lending requirements.
Accounting for Closing Costs, Property Taxes, and Ownership Expenses
Ontario property transactions involve expenses beyond the purchase price. Land transfer tax, legal fees, inspections, insurance, and closing adjustments can increase the initial financial commitment.
Eligible first-time homebuyers may qualify for Ontario’s provincial land transfer tax refund, currently capped at $4,000 under the established program. Eligibility depends on statutory conditions, including ownership history and residency requirements.
New Tecumseth property taxes also influence ongoing affordability. Actual tax obligations depend on assessed value, applicable municipal rates, and other relevant factors.
Hypothetical example: Consider a buyer purchasing a property for $750,000 with a 10% down payment. The initial down payment would equal $75,000. However, mortgage insurance, applicable taxes, legal expenses, and other closing costs require separate consideration.
The buyer should obtain a transaction-specific closing estimate before finalizing the purchase.
Examining Property Condition and Potential Ownership Risks
Property condition can significantly influence the true cost of homeownership. Even attractive homes may contain maintenance problems that are difficult to identify during an ordinary viewing.
Therefore, professional inspections and property documentation deserve attention before purchasers accept substantial contractual risks.
Why Professional Home Inspections Matter Before Purchasing
A qualified home inspector examines accessible building components and identifies visible conditions requiring attention. The assessment commonly covers roofing, foundations, plumbing, electrical systems, insulation, and heating equipment.
Inspectors may also identify signs of moisture intrusion, drainage problems, or deteriorating materials. However, inspections have limitations and cannot guarantee that every concealed defect will become apparent.
Inspection findings can influence negotiations, repair discussions, or a buyer’s willingness to proceed. Significant concerns may require additional evaluation by specialized contractors or licensed professionals.
Professional inspection costs are generally modest compared with potentially substantial repairs after possession.
Reviewing Renovation Records, Building Permits, and Property Disclosures
Major renovations may require municipal permits and compliance with applicable building regulations. Buyers should understand whether significant additions, structural alterations, or other regulated work received the necessary approvals.
Property disclosures and available renovation records can provide relevant historical information. However, buyers should not assume that seller disclosures identify every potential defect.
Hypothetical inspection scenario: A purchaser discovers signs of moisture near a finished basement wall. The inspector recommends further investigation because the visible condition does not establish the underlying cause.
The buyer may then seek professional assessment before deciding whether to proceed. This illustrates how inspection findings can influence financial decisions without relying on assumptions about repair costs.
Understanding Legal Responsibilities Before Signing a Purchase Agreement
A residential purchase agreement creates binding legal obligations once the parties accept its terms. Consequently, buyers should understand the document before submitting an offer.
Ontario’s real estate transaction process involves contractual conditions, deposit requirements, deadlines, and closing responsibilities. Professional legal guidance becomes particularly important when agreements contain unusual provisions.
Essential Clauses in Ontario’s Agreement of Purchase and Sale
The Agreement of Purchase and Sale identifies the property, purchase price, deposit, closing date, and other contractual terms. It may also specify included appliances, fixtures, and negotiated repairs.
Buyers should confirm that the written agreement accurately reflects their understanding of the transaction. Verbal discussions do not necessarily establish enforceable contractual obligations.
Important provisions include deposit arrangements, conditions, completion deadlines, and consequences of default. Certain circumstances may also require additional schedules or disclosure documents.
A real estate lawyer can review these provisions and explain their legal consequences before the purchaser becomes committed.
Financing Conditions, Inspection Clauses, and Buyer Protections
Conditional offers allow buyers to proceed subject to specified requirements. Common examples include financing approval, a satisfactory home inspection, or selling an existing property.
These conditions may provide important contractual protections. However, their effectiveness depends on precise wording, deadlines, and compliance with the agreement.
Removing conditions can make an offer more attractive to certain sellers, but it may increase financial exposure. For example, a buyer could face serious consequences if financing becomes unavailable after submitting an unconditional offer.
Ontario’s real estate regulator encourages buyers to consider suitable contractual conditions and understand the risks of waiving them.
The Role of Real Estate Professionals and Legal Representation
Registered real estate professionals assist with market comparisons, property negotiations, and transaction documentation. Their responsibilities depend on the representation relationship and applicable Ontario regulations.
A real estate lawyer addresses legal questions, conducts title searches, and coordinates documentation required for closing. Lawyers also identify registered interests or contractual issues that may affect ownership.
Purchasers comparing new tecumseth houses for sale should understand these distinct professional roles. Coordinated professional advice provides greater clarity when complicated contractual or property concerns arise.
Developing a Competitive Offer Without Compromising Financial Security
A competitive offer should reflect property value, current market conditions, and the buyer’s financial capacity. Offering the highest possible amount does not necessarily represent the strongest purchasing decision.
Buyers should balance seller expectations with appropriate contractual protections and realistic ownership expenses.
Establishing a Reasonable Offer Through Evidence-Based Pricing
Recent comparable sales provide a useful starting point for determining an offer price. Buyers should also consider property condition, required repairs, available inventory, and relevant market competition.
For example, a recently renovated property may justify different pricing from a similar home requiring substantial maintenance. However, cosmetic upgrades alone do not establish market value.
Financial affordability should remain the primary boundary. Buyers should account for mortgage obligations and closing expenses before deciding how much to offer.
Professional market analysis can clarify whether the proposed amount aligns with available evidence.
Navigating Negotiations, Counteroffers, and Multiple-Offer Situations
Real estate negotiations involve more than the purchase price. Sellers may evaluate deposit arrangements, closing flexibility, financing conditions, and other contractual terms.
A counteroffer allows parties to propose alternative conditions before reaching an agreement. Multiple-offer situations may create additional pressure, particularly for desirable properties.
Hypothetical scenario: Buyer A offers $745,000 with financing and inspection conditions. Buyer B offers $750,000 with fewer conditions and a closing date preferred by the seller.
Although Buyer B proposes a higher price, both offers involve different contractual considerations. The seller may evaluate certainty, timing, and price before selecting an offer.
For buyers, preserving financial discipline remains essential regardless of competing interest.
Essential Considerations Before Making the Final Purchasing Decision
A successful property purchase should align with household needs, financial capacity, and long-term ownership expectations. Before committing, buyers should evaluate the property as both a living environment and a financial responsibility.
Reviewing Property Suitability and Long-Term Ownership Goals
Household requirements often change over time. Buyers should consider usable space, accessibility, commuting arrangements, and proximity to everyday amenities.
Property layout also deserves attention. A home with attractive finishes may still present practical limitations involving storage, parking, or functional living areas.
Long-term ownership expenses should influence the decision alongside immediate preferences. Buyers planning extended occupancy may place greater importance on maintenance requirements and neighbourhood stability.
Ultimately, suitability depends on individual circumstances rather than general market popularity.
Confirming Financial, Legal, and Property-Related Readiness
Before finalizing a property offer, purchasers should review five essential considerations:
- Property valuation: Does the proposed price align with comparable completed sales?
- Financial readiness: Are mortgage arrangements, closing expenses, and recurring costs manageable?
- Inspection findings: Have qualified professionals assessed significant property concerns?
- Legal obligations: Are contractual conditions, deadlines, and ownership requirements clearly understood?
- Long-term responsibilities: Does the property align with future household and maintenance expectations?
This final assessment creates a structured basis for deciding whether to proceed with the transaction.
Conclusion
Purchasing a home involves balancing property suitability, financial readiness, legal obligations, and local market conditions. Buyers should examine recent sales, compare neighbourhoods, and understand maintenance responsibilities before making a substantial commitment.
Professional inspections, realistic financing arrangements, and carefully reviewed purchase agreements can reduce avoidable uncertainty. Furthermore, evidence-based negotiations allow purchasers to make decisions without relying entirely on seller expectations or market speculation.
FAQs
Is New Tecumseth a Good Location for First-Time Homebuyers?
New Tecumseth may suit first-time buyers seeking residential communities with access to local amenities and regional transportation routes. However, affordability depends on property prices, financing capacity, and ongoing ownership expenses. Buyers should compare Alliston, Beeton, and Tottenham against their financial priorities and commuting requirements before selecting a location.
Which New Tecumseth Community Is Most Suitable for Families?
Alliston, Beeton, and Tottenham offer different residential environments, making suitability dependent on household preferences. Alliston provides broader commercial services, while Beeton offers a smaller community setting. Tottenham presents additional neighbourhood options and regional commuting considerations. Families should evaluate schools, healthcare access, recreation, and available housing before deciding.
How Can Buyers Determine a Fair Offer Price for a House?
Buyers can estimate a reasonable offer by reviewing recent comparable sales, property condition, location, and current inventory. Similar homes provide useful pricing evidence, although renovations and lot characteristics may justify differences. A registered real estate professional can interpret local transactions and explain how market competition affects negotiating conditions.
What Additional Expenses Should Buyers Expect Beyond the Purchase Price?
Buyers should budget for Ontario land transfer tax, legal fees, inspections, insurance, and applicable closing adjustments. Mortgage insurance may also apply, depending on financing arrangements. Property taxes, utilities, and maintenance create additional ownership costs. Eligible first-time purchasers should ask qualified professionals about applicable tax refunds and current requirements.
Can Buyers Negotiate House Prices in New Tecumseth?
Yes, buyers can negotiate property prices, although sellers retain discretion over acceptable offers. Negotiating opportunities depend on comparable sales, property condition, available inventory, and competing interest. Buyers should also consider closing dates and contractual conditions. A reasonable negotiation strategy balances market evidence with individual financial limitations.
What Happens After a Seller Accepts a Property Offer?
After acceptance, the purchaser must follow the agreement’s deposit requirements and contractual deadlines. Any included conditions require attention within the specified periods. The lender completes financing arrangements, while the lawyer handles title verification and closing documentation. Once the transaction closes successfully, the buyer receives possession according to the agreement.